

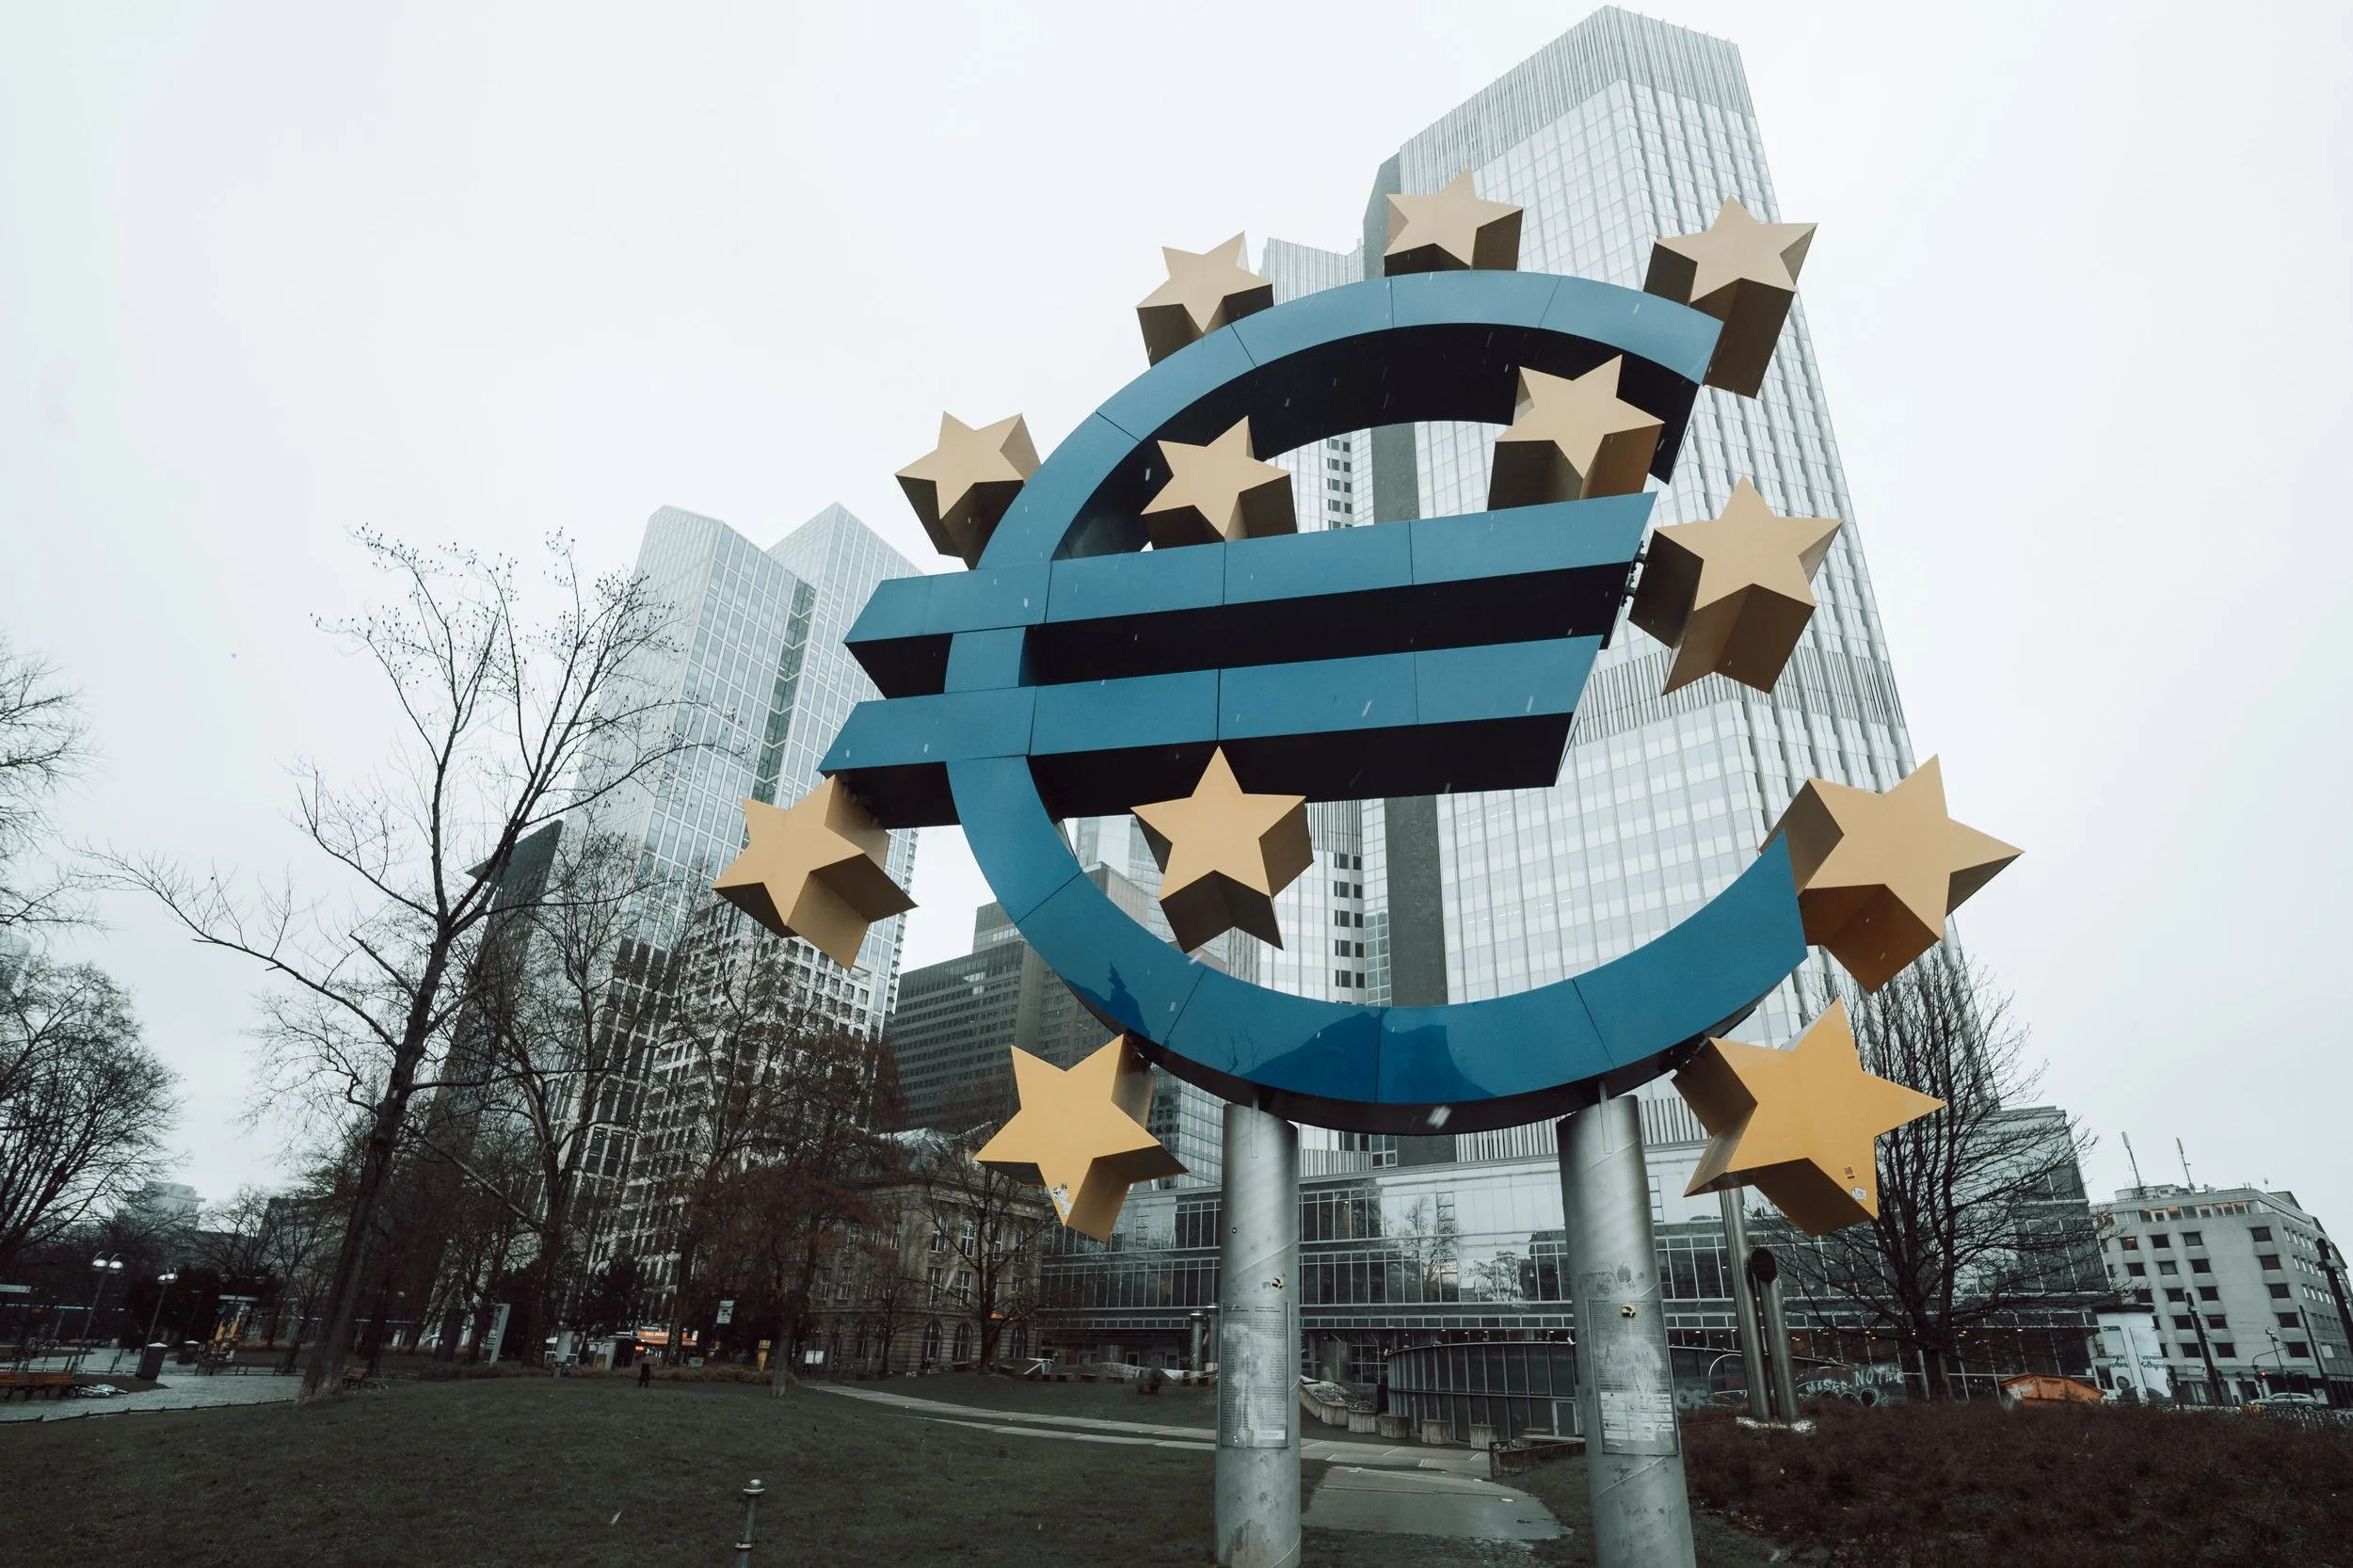
Iconic Euro sculpture in front of skyscrapers in Frankfurt during a winter day. Source: Pexels
Christine Lagarde’s farewell video message feels reassuring, almost calming. After nearly seven years at the head of the European Central Bank (ECB), the French lawyer announced she will be leaving her post on February 7th, 2027, eight months before her mandate was due to end. She further explained her decision by saying she wants the freedom to speak about issues beyond monetary policy, something her current position does not allow her to do. Still, she is hopeful, deeming the institution as prepared for whatever might come next. But what kind of future is the ECB preparing for, and who will shape it?
Lagarde’s resignation, announced on October 29th, ends months of speculation about her plans. No longer feeling comfortable in silence on broader global issues, particularly when she believed that the truth was being “damaged”, she argued that she still had something to contribute beyond central banking.
The first direct result of this decision is a vacuum for one of Europe’s most consequential positions of power at a time when the continent is facing a difficult economic and political outlook. The eurozone is struggling with relatively weak growth and persistent inflationary pressures, while France is approaching an election that could reshape the EU’s political balance. The choice for a successor is therefore not as straightforward as it seems.
The ECB’S mission is simple in theory: to maintain financial stability throughout the eurozone. In practice, however, doing so has become increasingly challenging. Lagarde took office in 2019, just before the Covid-19 pandemic. During her presidency, she also faced the aftermath of Russia’s invasion of Ukraine, conflicts in the Middle East, and Donald Trump’s tariffs and subsequent trade wars. With both inflation and uncertainty reaching new highs, supporting economic stability proved to be a much more difficult task.
These situations all exposed the limits of monetary policy. Interest rates are able to influence borrowing, spending, and inflation, but they cannot resolve Europe’s deeper economic problems: sluggish productivity, uneven growth, and the differing priorities of countries under the same currency. Precisely because decisions made in Frankfurt affect borrowers in Athens, the ECB rests its authority on the promise that decisions will be made in accordance with its mandate rather than on the interests of particular governments.
But that promise now enters sensitive territory. Under the EU’s appointment process, the ECB president is selected following a series of recommendations and consultations with both the European Parliament and the ECB’s governing body. National governments therefore have an important role to play in selecting who will lead an institution expected to operate independently of political pressure.
Lagarde’s early departure means that this process will now most likely take place before France’s presidential election in April 2027. Marine Le Pen’s far-right National Rally is expected to make significant inroads and emerge in a stronger position. The next ECB president will be chosen not only amid economic uncertainty, but also as one of the EU’s founding members could shift further towards increasingly nationalist, Eurosceptic politics. Even though central banks are meant to be insulated from short-term political demands so they can make potentially unpopular but necessary decisions, their leadership is still determined by the same recurring political negotiations and ideological preferences of necessarily biased people.
The succession will also resurface questions about national representation and fiscal priorities. Potential candidates include former Dutch central bank president Klaas Knot, former Spanish central bank governor Pablo Hernández de Cos, Bundesbank president Joachim Nagel and European Investment Bank president Nadia Calviño. Each would arrive with a unique professional background and different views on how to best tackle the ever-evolving challenges faced by the eurozone. If this succession becomes a proxy battle over the EU’s future economic direction, the ECB will have to put in tremendous effort to prove that political bargaining over its leadership does not translate into political control over its decisions.
Nonetheless, Lagarde’s departure does not mean that the ECB’s policies will change overnight, nor does its president have unilateral control of policymaking. Ultimately, monetary policy is set collectively by the governing council. The more important question is whether the next president can maintain confidence in the established systems in an environment where the potential for crisis and division continues to grow.
There is no reason why Lagarde’s declaration that the ECB is “fit for the future” would not prove accurate. But nor is there a reason to think it would. Europe does not need the ECB to be politically influential. It needs it to be reliable and economically credible. The question is who will replace her, but also whether this decision can remain at the margins of wider political tension.